Hire Purchase
Spread the cost towards ownership.
- Fixed monthly repayments
- Own the asset at the end
Finance for the vehicles, equipment and opportunities that move your business forward.
Find your financeChoose what you need. We’ll help you find the right route.
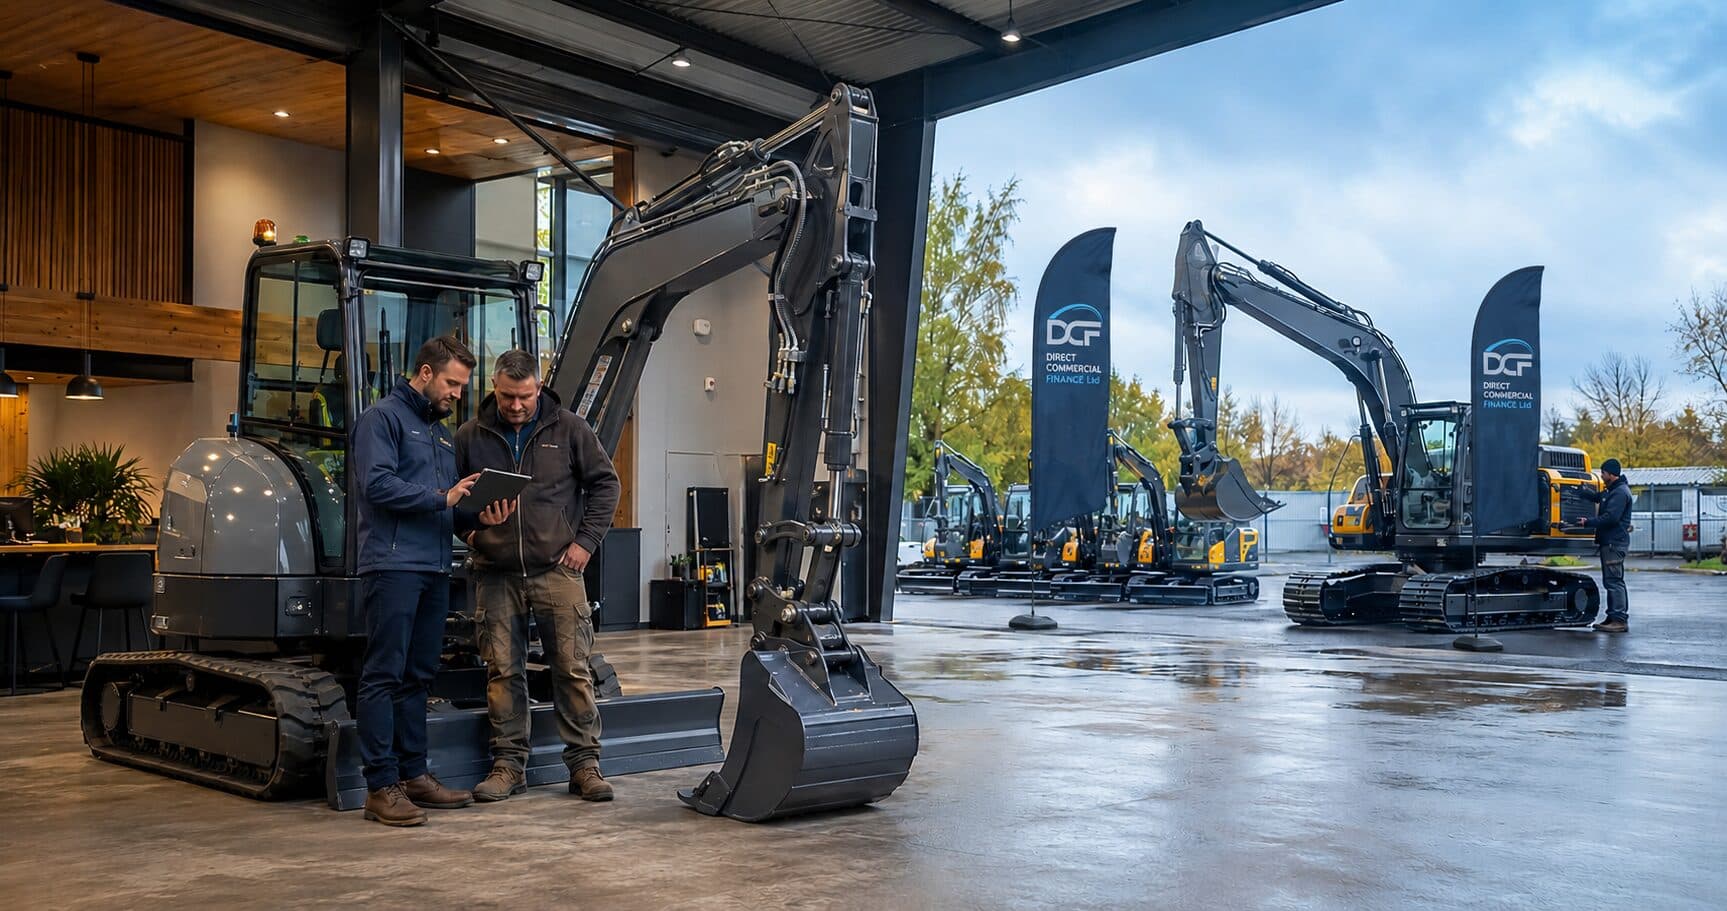
Get the equipment you need to grow.
Explore asset finance
Unlock cash tied up in your invoices.
Explore invoice finance
Find and finance the right vehicles and assets.
Explore vehicle sourcing
Finance for your property and larger plans.
Explore commercial loansFlexible finance to support your sales.
Explore vendor financeSpread the cost towards ownership.
Use the asset with regular rentals.
Release value from existing assets.
Funding 20 used tractor units for a growing haulage business, structured to keep cash in the business while meeting a new contract commitment.
Read the case studyExplore who each solution suits and how it works.
Spread the cost of vehicles, plant and equipment over time instead of tying up capital. We match you with the lender best suited to your sector and asset type — new or used.
Any UK limited company buying vehicles, plant or equipment — from a single van to a full fleet, new or used.
We structure the deal as one of two main agreement types, Hire Purchase or a Finance Lease, or refinance an asset you already own — whichever fits your cash position and how long you plan to keep the asset. Here's the difference:
Hire Purchase · Finance Lease · Refinance
Enquire about asset financeTurn unpaid invoices into working capital, often within 24 hours of approval. Ideal for businesses with long payment terms who need cash flow now, not in 60 days.
Businesses invoicing on 30, 45 or even 90-day terms who don’t want to wait that long to get paid.
Rather than waiting out your customers’ payment terms, we arrange for up to 95% of an invoice’s value to be released to you as soon as it’s approved — the remainder follows, less fees, once your customer settles.
Enquire about invoice financeWe source the vehicle or equipment and arrange the finance in one process — saving you the back-and-forth of dealing with sourcing and funding separately.
Businesses that need a van, car, HGV or specialist vehicle — or any piece of equipment — sourced as well as financed.
We’ve built direct relationships with major manufacturers over many years, giving us access to pricing other buyers simply don’t have — often below what you’d pay even at a main dealer. Tell us the spec, and we handle sourcing and finance together as one process.
Enquire about vehicle & asset sourcingFunding for property purchase, refinance, or business expansion — structured against your business's actual trading position, not a generic checklist.
Businesses purchasing land for development, a new yard for expansion or relocation, or simply looking to boost their cash flow.
We look at how your business actually trades, not a generic checklist, and structure the loan or mortgage around that — whether you’re buying, refinancing, or expanding.
Enquire about commercial loans & mortgagesPoint-of-sale finance for your customers, arranged and administered by us — so you can close bigger deals without carrying the credit risk yourself.
Suppliers of machinery, equipment, IT equipment or anything else sold to commercial customers.
We offer finance to your customers at the point of sale and handle the administration ourselves — so you can close bigger deals and increase sales, without carrying the credit risk or the paperwork.
Enquire about vendor financeThe most common type of asset finance. You pay a deposit, then fixed monthly repayments over a term that suits you. You own the asset once the agreement is repaid in full, and it sits on your balance sheet with the same tax advantages as an outright purchase.
A way to acquire an asset without owning it outright. VAT is charged on each rental rather than paid upfront, and the rental payments can be offset against taxable profits. At the end of the term you can either continue using the asset for a small secondary rental, or sell it and keep the majority of the proceeds (generally around 95%).
Releasing value from an asset you already own. We can refinance an existing agreement — depending on your equity position, this can lower your repayments or extend the term — or, if you hold unencumbered assets, finance them for up to 95% of their current value to boost your cash position.
DCF is a whole-of-market commercial finance broker, not a lender. We work across a panel of UK lenders to match your business with the option best suited to your situation and asset type, rather than offering a single in-house product.
DCF arranges asset finance, invoice finance, vehicle and asset sourcing, commercial loans and mortgages, and vendor finance for UK limited companies.
DCF arranges commercial and asset finance for UK limited companies, from single vehicles and machines to full fleets.
Decisions are often same-day, though timing depends on the lender and the complexity of your application. DCF has been funding UK businesses since 2011 with direct access to lender decision-makers.
With Hire Purchase you pay a deposit and fixed monthly repayments, and you own the asset once the agreement is repaid in full. With a Finance Lease you don’t own the asset at the end — instead you can pay a small secondary rental to keep using it, or sell it and keep the majority of the proceeds. Finance Lease VAT is charged on each rental rather than upfront, which is why it’s often favoured by newer businesses or anywhere cash flow needs to be conserved.
Generally yes for Hire Purchase, alongside VAT which is usually paid upfront (though VAT deferral of up to 3 months, and in some cases 0% VAT, is available). A Finance Lease typically needs less capital outlay to get started. Exact amounts depend on the asset, lender and your business’s position — we’ll confirm the specifics for your deal.
Yes — this is Refinance. If you hold unencumbered assets, we can finance them for up to 95% of their current value. If you already have a finance agreement in place, we can also look at refinancing it to lower your repayments or extend the term, depending on your equity position.
Up to 95% of an invoice’s value, often within 24 hours of approval — the remainder follows, less fees, once your customer pays. It’s built for businesses on long payment terms (30, 45 or even 90 days) who need the cash sooner.
Both. We arrange finance for vehicles (vans, cars, HGVs and specialist vehicles) as well as plant, machinery and equipment — from a single asset to a full fleet. For vehicles specifically, we can also source the vehicle itself through our manufacturer relationships, not just arrange the finance.
It varies by deal, but once finance is agreed we’ll typically ask for recent bank statements, company accounts and a form of ID (such as a driving licence) to complete the funding. We’ll confirm exactly what’s needed for your specific application.